Buy business-development.eu ?
We are moving the project
business-development.eu .
Are you interested in purchasing the domain
business-development.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy business-development.eu ?
What is the difference between a business administration maturity loan and an installment loan?
A business administration maturity loan is a type of loan that is typically used for long-term financing needs, such as purchasing equipment or real estate. It has a fixed maturity date and is usually repaid in regular installments over a longer period of time. On the other hand, an installment loan is a type of loan that is repaid in equal, regular payments over a set period of time, which can be short or long term. While both types of loans involve regular payments, the business administration maturity loan is specifically designed for business needs and often involves larger amounts of money for longer-term investments. **
What exactly is an instant loan or online loan?
An instant loan or online loan is a type of loan that allows individuals to apply for and receive funds quickly through an online platform. These loans typically have a simple application process that can be completed online, and the approval and disbursement of funds can happen within a short period of time, sometimes within minutes. Instant loans are often used for emergency expenses or unexpected financial needs, and they may have higher interest rates or fees compared to traditional bank loans. **
Similar search terms for Loan
Top-Angebote
Products related to Loan:
-
Little Brown Book Group No Limits: Blow the Cap Off Your Capacity by John C. Maxwell – Personal Growth & Leadership Development GuideNo Limits: Blow the CAP Off Your Capacity Description We often treat the word capacity as if it were a natural law of limitation. Unfortunately; most of us are much more comfortable defining what we perceive is off limits rather than what's possible. Could it be that many people have allowed what they perceive as capacity to define them? Have they allowed their perception to limit their attitudes about their potential? In his newest book; John Maxwell identifies 17 core capacities. Some of these are abilities we all already possess; such as energy; creativity and leadership. Others are aspects of our lives controlled by our choices; like our attitudes; character; and intentionality. Maxwell examines each of these 17 capacities; and provides clear and actionable advice on how you can increase your potential in each. He will guide you on how to identify; grow; and apply your critical capacities to your daily life. Once you've blown the 'cap' off your capacities; you'll find yourself more successful--and fulfilled--in your daily life.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
DK The Month-by-Month Baby Book: In-depth, Monthly Advice on Your Baby's Growth, Care, and Development in the First YearThe only book new parents will need for the extraordinary first year of their baby's life. This comprehensive book covers every moment of the first twelve months of your baby's life - from their first moments at home, feeding, and sleeping arrangements, to travelling, building their body strength, and starting to eat solids. A team of expert paediatricians, midwives, psychologists, and nutritionists provide unrivalled detail on everything new parents can expect. This new edition has been updated with the latest medical advice for a new generation of parents, and includes reassuring answers to common questions, offering additional support for whenever you need it. The Month-by-Month Baby Book perfectly complements the bestselling The Day-by-Day Pregnancy Book.16,99 £*Shipping: 2,99 £Secure redirect to the provider
-
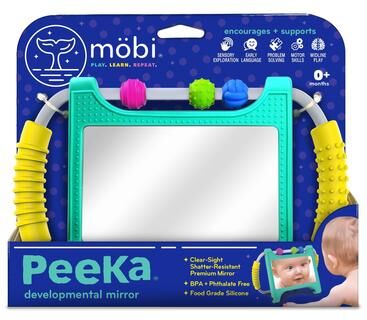
Mobi Peeka Development MirrorPEEKA® developmental mirror was designed by our team of doctors, therapists and parents to help children explore, learn and grow. When you place PEEKA® in the hands of your little ones, you will be amazed at the variety of ways they find to play...26,99 $*Shipping: 0,00 $Secure redirect to the provider
-
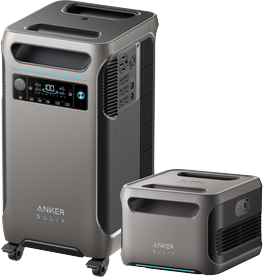
soundcore Anker SOLIX F3800 + Expansion Battery - 7680Wh 6000WSolar Input: Up to 2,400W (dual 60V) solar charging, fully charges in <2 hours in optimal sunlight. Scalability: Starts at 3.84kWh (6kW), expandable to 53.8kWh (12kW) for days-to-week-long backup. Dual Voltage: 120V/240V, 6,000W AC output per unit,...6498,00 $*Shipping: 0,00 $Secure redirect to the provider
-
What is the difference between loan coinage and loan meaning?
Loan coinage refers to the process of borrowing words from one language and incorporating them into another language, often with some modification to fit the phonological and morphological patterns of the borrowing language. Loan meaning, on the other hand, refers to the borrowing of the semantic or conceptual content of a word from one language to another, without necessarily adopting the actual word itself. In other words, loan coinage involves borrowing the word itself, while loan meaning involves borrowing the underlying concept or meaning. **
-
What is the difference between a loan and a loan?
A loan is a sum of money that is borrowed from a lender with the agreement to pay it back over time, usually with interest. On the other hand, a loan is a verb that refers to the act of lending something, typically money, to someone else. In essence, a loan is the actual financial transaction, while to loan is the action of providing that financial assistance. **
-
Can an unemployed person start a business with a loan?
Yes, an unemployed person can start a business with a loan. However, they may face challenges in securing a loan without a steady income or employment history. Lenders typically look for a source of income to ensure repayment of the loan. The unemployed individual may need to provide a solid business plan, collateral, or a co-signer to increase their chances of getting approved for a loan. It is important for them to carefully consider the risks and ensure they have a viable plan for generating income before taking on debt to start a business. **
-
Is leasing a loan?
No, leasing is not a loan. Leasing involves renting an asset for a specific period of time in exchange for regular payments, while a loan involves borrowing money that must be repaid with interest. **

What are loan debts?
Loan debts are money that an individual or entity owes to a lender as a result of borrowing funds. This debt must be repaid according to the terms and conditions outlined in the loan agreement, which typically include the amount borrowed, the interest rate, and the repayment schedule. Failure to repay a loan debt can result in penalties, fees, and damage to the borrower's credit score. **
What is the difference between a bank loan and a passive loan?
A bank loan is a traditional loan provided by a financial institution, such as a bank, where the borrower receives a lump sum of money and is required to make regular payments, including interest, over a set period of time. The borrower is actively involved in the loan process, including applying for the loan, providing documentation, and making payments. On the other hand, a passive loan is a type of investment where an individual or entity provides funds to a borrower, typically through a peer-to-peer lending platform, and receives regular interest payments in return. The lender is not actively involved in the day-to-day management of the loan, as the platform typically handles the loan origination, servicing, and collection of payments. In summary, the main difference between a bank loan and a passive loan is the role of the lender: in a bank loan, the lender is a financial institution providing a lump sum of money, while in a passive loan, the lender is an individual or entity providing funds as an investment. **
Top-Angebote
Products related to Loan:
-
Harvard Business Review Press Blue Ocean Strategy, Expanded Edition: How to Create Uncontested Market Space and Make the Competition IrrelevantThe global phenomenon that has sold over 4 million copies, is published in a record-breaking 49 languages and is a bestseller across five continents—now updated and expanded with new content. Named by Fast Company as one of the most influential leadership books in its Leadership Hall of Fame. A strategy classic. In this perennial bestseller, embraced by organizations and industries worldwide, globally preeminent management thinkers W. Chan Kim and Renée Mauborgne challenge everything you thought you knew about the requirements for strategic success. Recognized as one of the most iconic and impactful strategy books ever written, BLUE OCEAN STRATEGY, now updated with fresh content from the authors, argues that cutthroat competition results in nothing but a bloody red ocean of rivals fighting over a shrinking profit pool. Based on a study of 150 strategic moves (spanning more than 100 years across 30 industries), the authors argue that lasting success comes not from battling competitors but from creating "blue oceans"—untapped new market spaces ripe for growth. BLUE OCEAN STRATEGY presents a systematic approach to making the competition irrelevant and outlines principles and tools any organization can use to create and capture their own blue oceans. This expanded edition includes: A new preface by the authors: Help! My Ocean Is Turning Red Updates on all cases and examples in the book, bringing their stories up to the present time Two new chapters and an expanded third one—Alignment, Renewal, and Red Ocean Traps—that address the most pressing questions readers have asked over the past 10 years A landmark work that upends traditional thinking about strategy, this bestselling book charts a bold new path to winning the future. Consider this your guide to creating uncontested market space—and making the competition irrelevant. To learn more about the power of BLUE OCEAN STRATEGY, visit blueoceanstrategy.com. There you'll find all the resources you need—from ideas in practice and cases from government and private industry, to teaching materials, mobile apps, real-time updates, and tips and tools to help you make your blue ocean journey a success.14,99 £*Shipping: 2,99 £Secure redirect to the provider
-
HARPERCOLLINS Creative Confidence by Tom & David Kelley – Unleashing Your Creative Potential & Innovation MindsetA powerful and inspiring book from the founders of IDEO, the award-winning design firm, on unleashing the creativity that lies within each and every one of us. Too often, companies and individuals assume that creativity and innovation are the domain of the ‘creative types’. But two of the foremost experts in innovation, design and creativity on the planet show us that each and every one of us is creative. In an entertaining and inspiring narrative that draws on countless stories from their work at IDEO, and with many of the world's top companies and design firms, David and Tom Kelley identify the principles and strategies that will allow us to tap into our creative potential in our work lives, and in our personal lives, allow us to think outside the box in terms of how we approach and solve problems. ‘Creative Confidence’ is a book that will help each of us be more productive and successful in our lives and in our careers.4,95 £*Shipping: 1,99 £Secure redirect to the provider
-
Little Brown Book Group No Limits: Blow the Cap Off Your Capacity by John C. Maxwell – Personal Growth & Leadership Development GuideNo Limits: Blow the CAP Off Your Capacity Description We often treat the word capacity as if it were a natural law of limitation. Unfortunately; most of us are much more comfortable defining what we perceive is off limits rather than what's possible. Could it be that many people have allowed what they perceive as capacity to define them? Have they allowed their perception to limit their attitudes about their potential? In his newest book; John Maxwell identifies 17 core capacities. Some of these are abilities we all already possess; such as energy; creativity and leadership. Others are aspects of our lives controlled by our choices; like our attitudes; character; and intentionality. Maxwell examines each of these 17 capacities; and provides clear and actionable advice on how you can increase your potential in each. He will guide you on how to identify; grow; and apply your critical capacities to your daily life. Once you've blown the 'cap' off your capacities; you'll find yourself more successful--and fulfilled--in your daily life.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
DK The Month-by-Month Baby Book: In-depth, Monthly Advice on Your Baby's Growth, Care, and Development in the First YearThe only book new parents will need for the extraordinary first year of their baby's life. This comprehensive book covers every moment of the first twelve months of your baby's life - from their first moments at home, feeding, and sleeping arrangements, to travelling, building their body strength, and starting to eat solids. A team of expert paediatricians, midwives, psychologists, and nutritionists provide unrivalled detail on everything new parents can expect. This new edition has been updated with the latest medical advice for a new generation of parents, and includes reassuring answers to common questions, offering additional support for whenever you need it. The Month-by-Month Baby Book perfectly complements the bestselling The Day-by-Day Pregnancy Book.16,99 £*Shipping: 2,99 £Secure redirect to the provider
-
What is the difference between a business administration maturity loan and an installment loan?
A business administration maturity loan is a type of loan that is typically used for long-term financing needs, such as purchasing equipment or real estate. It has a fixed maturity date and is usually repaid in regular installments over a longer period of time. On the other hand, an installment loan is a type of loan that is repaid in equal, regular payments over a set period of time, which can be short or long term. While both types of loans involve regular payments, the business administration maturity loan is specifically designed for business needs and often involves larger amounts of money for longer-term investments. **
-
What exactly is an instant loan or online loan?
An instant loan or online loan is a type of loan that allows individuals to apply for and receive funds quickly through an online platform. These loans typically have a simple application process that can be completed online, and the approval and disbursement of funds can happen within a short period of time, sometimes within minutes. Instant loans are often used for emergency expenses or unexpected financial needs, and they may have higher interest rates or fees compared to traditional bank loans. **
-
What is the difference between loan coinage and loan meaning?
Loan coinage refers to the process of borrowing words from one language and incorporating them into another language, often with some modification to fit the phonological and morphological patterns of the borrowing language. Loan meaning, on the other hand, refers to the borrowing of the semantic or conceptual content of a word from one language to another, without necessarily adopting the actual word itself. In other words, loan coinage involves borrowing the word itself, while loan meaning involves borrowing the underlying concept or meaning. **
-
What is the difference between a loan and a loan?
A loan is a sum of money that is borrowed from a lender with the agreement to pay it back over time, usually with interest. On the other hand, a loan is a verb that refers to the act of lending something, typically money, to someone else. In essence, a loan is the actual financial transaction, while to loan is the action of providing that financial assistance. **
Similar search terms for Loan
-
Mobi Peeka Development MirrorPEEKA® developmental mirror was designed by our team of doctors, therapists and parents to help children explore, learn and grow. When you place PEEKA® in the hands of your little ones, you will be amazed at the variety of ways they find to play...26,99 $*Shipping: 0,00 $Secure redirect to the provider
-
soundcore Anker SOLIX F3800 + Expansion Battery - 7680Wh 6000WSolar Input: Up to 2,400W (dual 60V) solar charging, fully charges in <2 hours in optimal sunlight. Scalability: Starts at 3.84kWh (6kW), expandable to 53.8kWh (12kW) for days-to-week-long backup. Dual Voltage: 120V/240V, 6,000W AC output per unit,...6498,00 $*Shipping: 0,00 $Secure redirect to the provider
-
soundcore Anker SOLIX C2000 Gen 2 + Expansion BatteryUltra-Efficient Power for Longer Runtime: Only 9W idle power consumption , powering a dual-door fridge for up to 32 hours. Up to 4kWh Expandable Capacity: With a BP2000 (Gen 2) Expansion Battery, C2000 Gen 2 can keep a dual-door fridge running for...2498,00 $*Shipping: 0,00 $Secure redirect to the provider
-
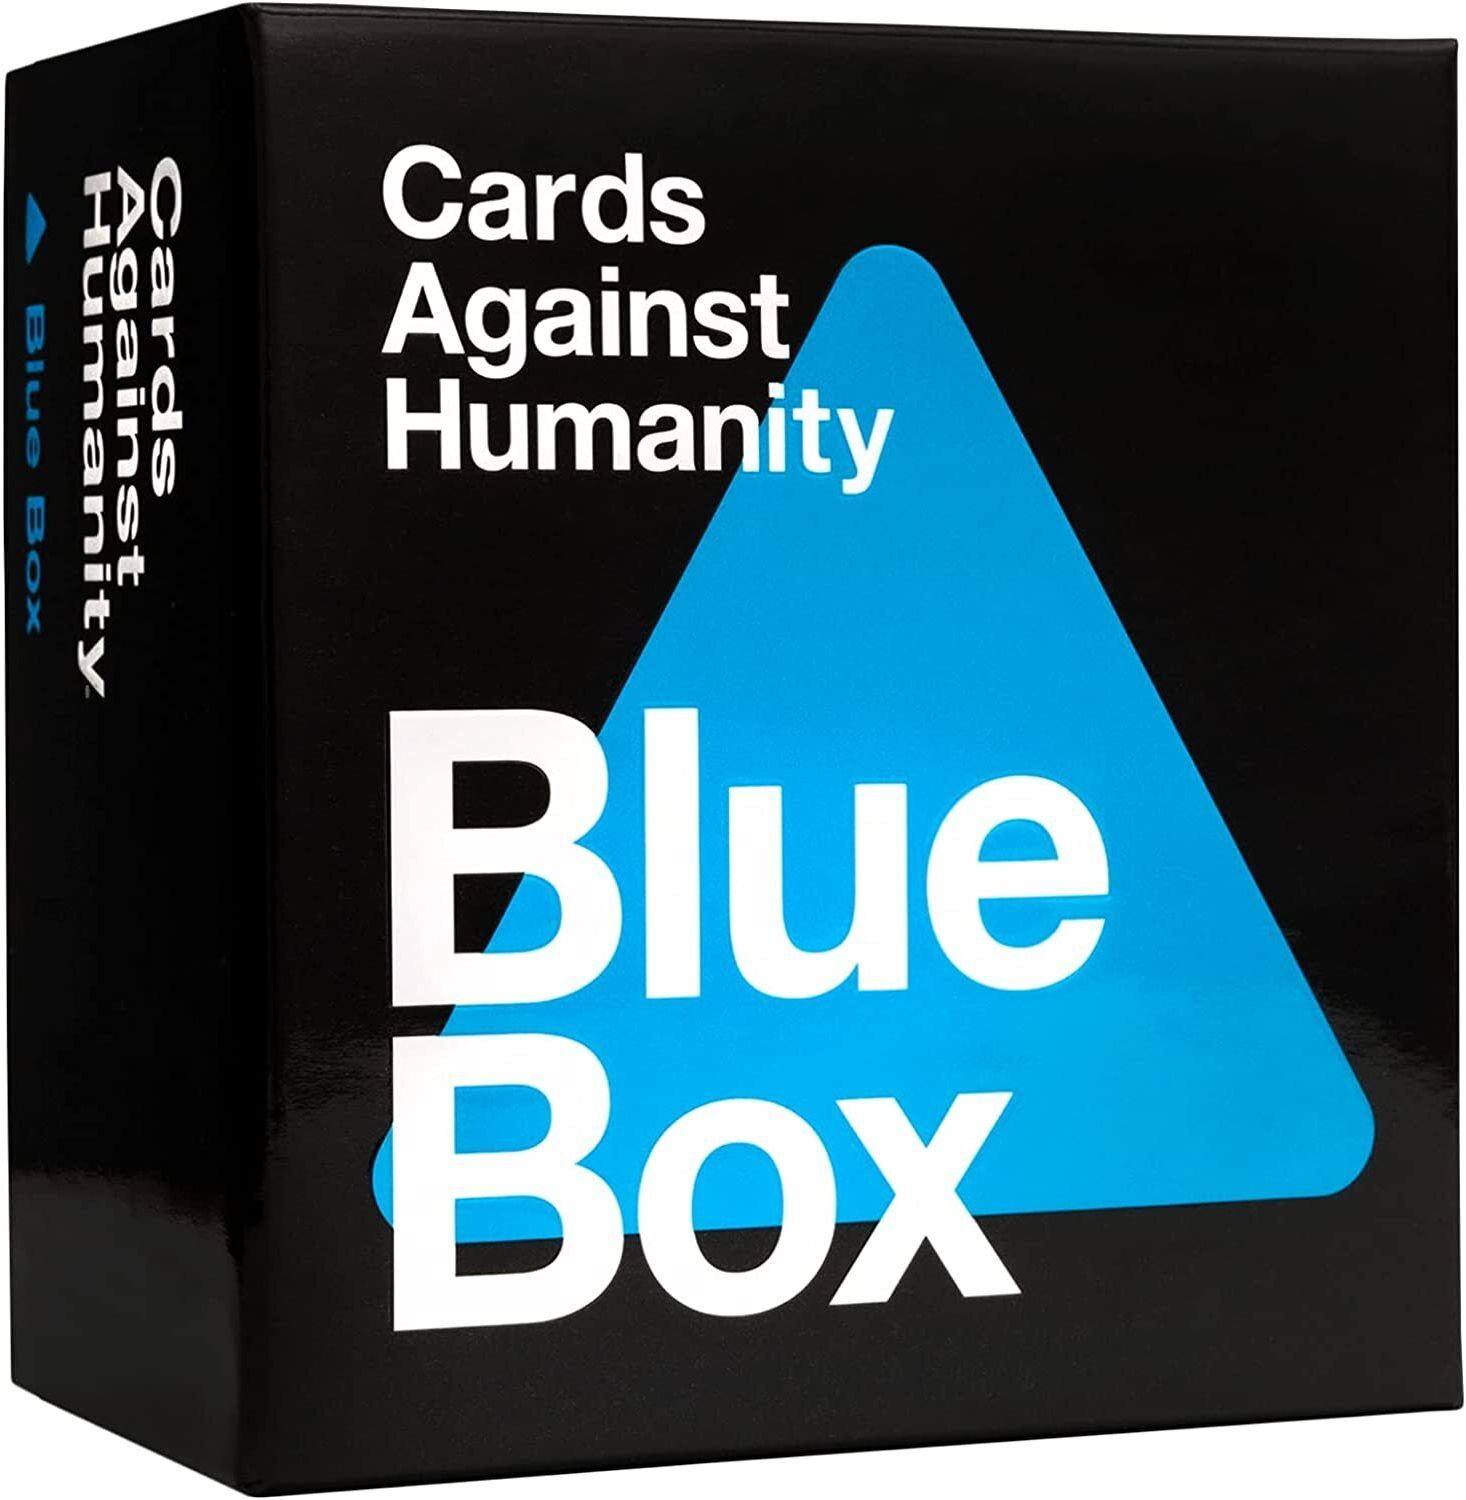
Cards Against Humanity – Blue Box Expansion (300 Cards)The Cards Against Humanity Blue Box is a 300-card expansion that adds a huge dose of fresh, outrageous content to the original Cards Against Humanity game. Carefully curated from years of new material, the Blue Box delivers bigger laughs, unexpected combinations and extended replay value for adult game nights and parties. Key Features 300 additional cards to expand Cards Against Humanity Features newer content compared to earlier expansions Seamlessly integrates with the base game and other expansion boxes Simple to add – just shuffle and play Premium-quality cards in the classic Cards Against Humanity style Designed strictly for adult players Benefits The Blue Box keeps Cards Against Humanity feeling fresh by injecting a large volume of modern content into your deck. Ideal for regular players, it dramatically increases variety and replayability without adding complexity. A must-have expansion for fans who want more laughs and longer game sessions. Specifications Table Specification Details Brand Cards Against Humanity Product Type Card Game Expansion Expansion Name Blue Box Card Count 300 Compatibility Cards Against Humanity Base Game Recommended Age 18+ Players Group Play Language English Colour Blue Box EAN / Barcode 817246020040 Ideal for adults aged 18+ who already own Cards Against Humanity and want to expand their collection. Perfect for parties, game nights and social gatherings where bold, irreverent humour is welcome.20,99 £*Shipping: 0,00 £Secure redirect to the provider
-
Can an unemployed person start a business with a loan?
Yes, an unemployed person can start a business with a loan. However, they may face challenges in securing a loan without a steady income or employment history. Lenders typically look for a source of income to ensure repayment of the loan. The unemployed individual may need to provide a solid business plan, collateral, or a co-signer to increase their chances of getting approved for a loan. It is important for them to carefully consider the risks and ensure they have a viable plan for generating income before taking on debt to start a business. **
-
Is leasing a loan?
No, leasing is not a loan. Leasing involves renting an asset for a specific period of time in exchange for regular payments, while a loan involves borrowing money that must be repaid with interest. **
-
What are loan debts?
Loan debts are money that an individual or entity owes to a lender as a result of borrowing funds. This debt must be repaid according to the terms and conditions outlined in the loan agreement, which typically include the amount borrowed, the interest rate, and the repayment schedule. Failure to repay a loan debt can result in penalties, fees, and damage to the borrower's credit score. **
-
What is the difference between a bank loan and a passive loan?
A bank loan is a traditional loan provided by a financial institution, such as a bank, where the borrower receives a lump sum of money and is required to make regular payments, including interest, over a set period of time. The borrower is actively involved in the loan process, including applying for the loan, providing documentation, and making payments. On the other hand, a passive loan is a type of investment where an individual or entity provides funds to a borrower, typically through a peer-to-peer lending platform, and receives regular interest payments in return. The lender is not actively involved in the day-to-day management of the loan, as the platform typically handles the loan origination, servicing, and collection of payments. In summary, the main difference between a bank loan and a passive loan is the role of the lender: in a bank loan, the lender is a financial institution providing a lump sum of money, while in a passive loan, the lender is an individual or entity providing funds as an investment. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.